Planning for Healthcare in Retirement: What to Know Before You Leave the Workforce
When people think about retirement planning, they often focus on savings goals and investment strategies. But one critical piece is sometimes overlooked:
Healthcare planning.
Healthcare costs are not optional in retirement — and they tend to rise faster than general inflation. That’s why incorporating healthcare expenses into your retirement strategy early can make a meaningful difference in long-term financial confidence.
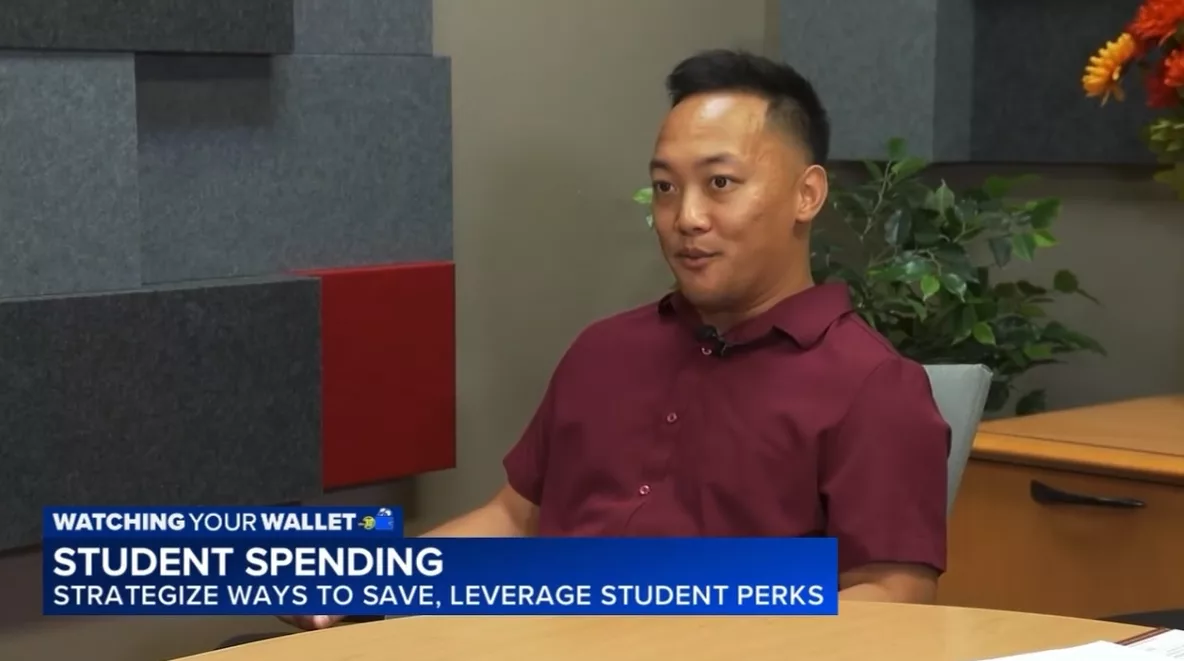
Recently, the team at Portfolio Advisors Inc. shared key considerations on ABC30’s Watching Your Wallet to help individuals better prepare for this important transition.
Why Healthcare Costs Matter in Retirement
Healthcare expenses often increase over time and can significantly impact cash flow in retirement. Unlike many other expenses, they are also less predictable — making advance planning especially important.
Factoring healthcare costs into your retirement plan allows you to:
- Set realistic income expectations
- Avoid surprises during the early retirement years
- Preserve flexibility as medical needs evolve
Planning ahead helps ensure your savings are supporting both your lifestyle and your health.
Understanding Medicare Before You Retire
Medicare can be complex, and timing matters.
A strong starting point is developing a clear understanding of Medicare’s components 6 to 12 months before retirement. This allows time to evaluate coverage options, costs, and enrollment deadlines without pressure.
It’s also important to understand the gap that can occur if you retire before age 65. Individuals who leave the workforce earlier may need to secure private health insurance for several years before becoming eligible for Medicare — which can significantly impact retirement cash flow.
Choosing Coverage That Fits Your Situation
Healthcare planning isn’t one-size-fits-all. When evaluating insurance options, it’s helpful to consider:
- Expected retirement income and cash flow
- Affordability of premiums and out-of-pocket costs
- Family medical history and long-term care considerations
In some cases, long-term care insurance may be worth exploring. Understanding your state’s specific rules and available programs is also important, as some care costs may be supported through state resources alongside personal savings.
Using Health Savings Accounts Strategically
Health Savings Accounts (HSAs) can play a valuable role in retirement planning.
While HSAs typically require a minimum cash balance, funds beyond that amount may be eligible for investment. This can allow your healthcare dollars to grow over time, potentially supporting future medical expenses in retirement.
When used thoughtfully, HSAs can provide both flexibility and tax advantages.
Don’t Overlook Flexible Spending Accounts
Some employers offer Flexible Spending Accounts (FSAs), which often come with “use-it-or-lose-it” rules. To make the most of these benefits, it’s important to review balances regularly — monthly or quarterly — and plan expenses accordingly.
Staying on top of these accounts helps ensure you’re maximizing available benefits rather than leaving money unused.
Planning Ahead for Peace of Mind
Healthcare planning is a critical part of retirement readiness — and one that benefits from early, thoughtful attention.
By understanding Medicare timelines, planning for potential coverage gaps, and using tools like HSAs and FSAs strategically, retirees can approach this transition with greater confidence and clarity.
If you’d like help incorporating healthcare planning into your retirement strategy, our team is here to support you.
Portfolio Advisors Inc. is grateful to ABC30 and Vanessa Vasconcelos for spotlighting this important conversation in their Watching Your Wallet segment and helping educate couples throughout the Central Valley about building strong, transparent financial habits.
For more financial tips and planning resources, visit our Knowledge Center.